Those who sell specialised industrial machinery tend to assume their customers come from trade shows, local agents and word of mouth.
And they are right — for the customers they already know.
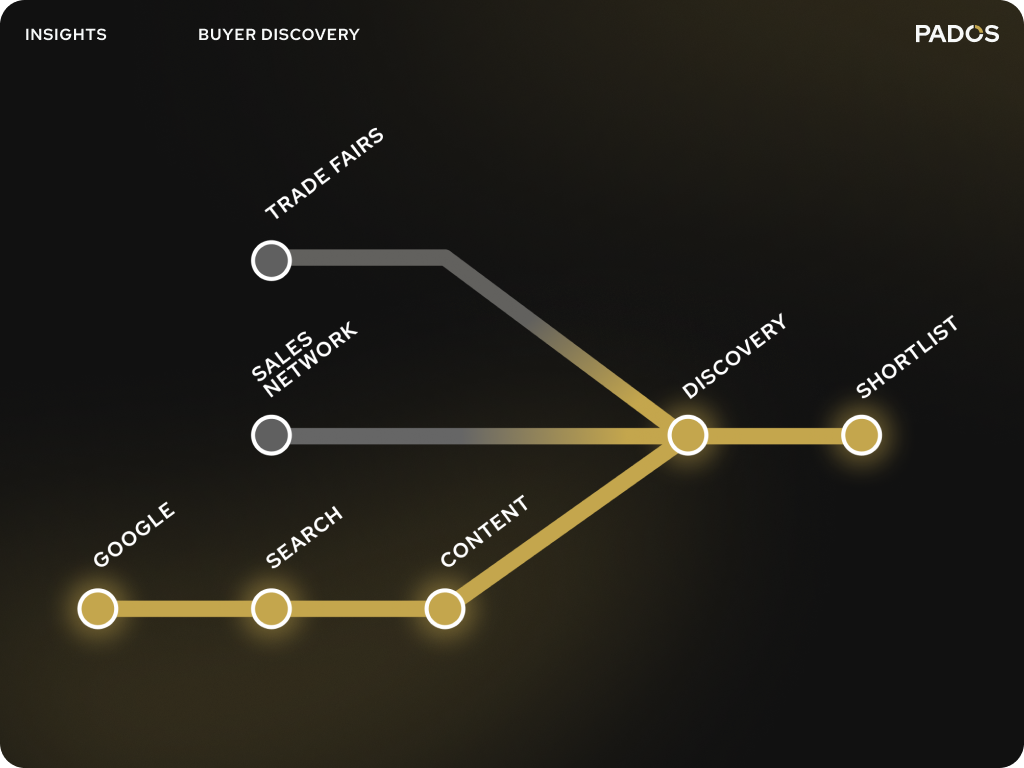
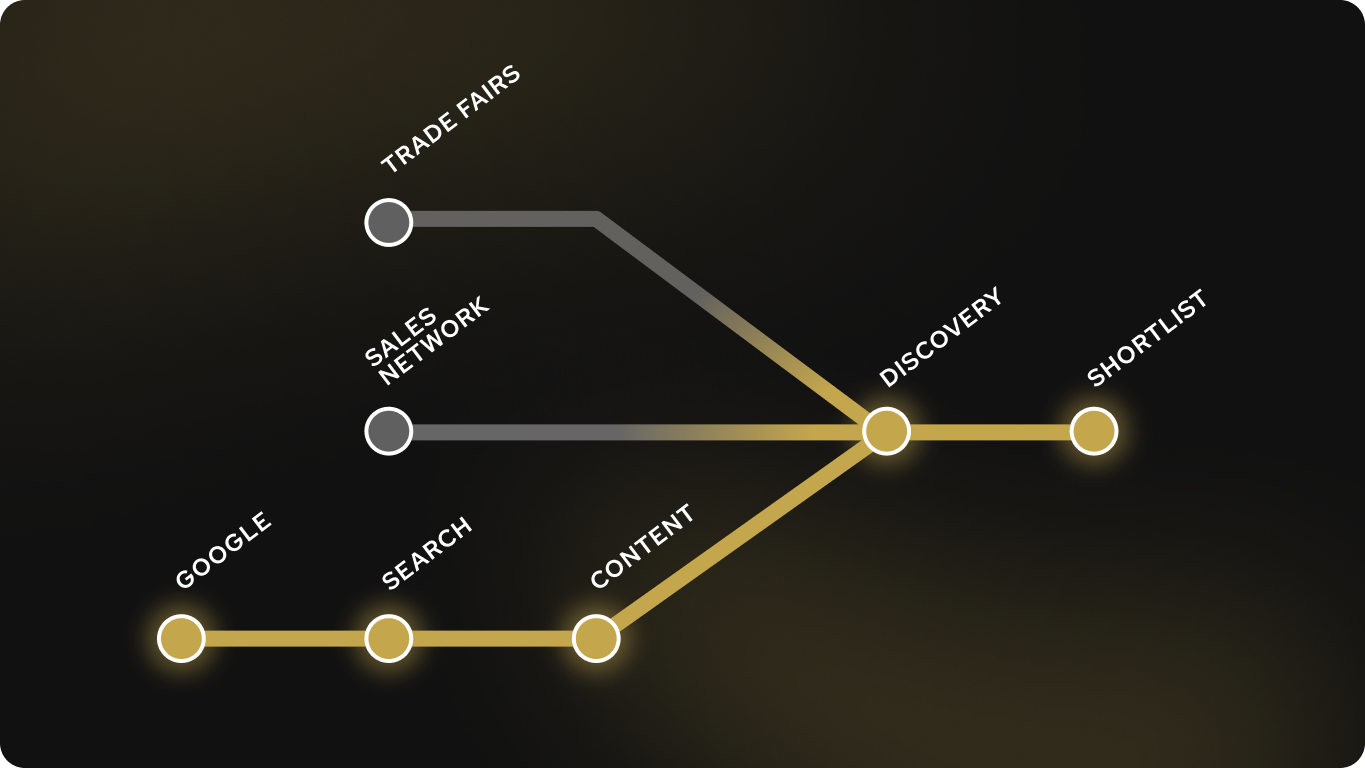
The problem is everything else: buyers who are searching, do not yet know who to approach, and start with Google.
This is the gap that the market research we are presenting identified systematically across an international sample of manufacturers.
An Export-Driven Market With a Digital Paradox
The specialised industrial machinery sector is structurally export-oriented.
In many Italian specialised manufacturing subsectors, more than 70% of production is sold outside Italy — to Asia, Latin America, Eastern Europe and North Africa.
This has a direct implication: the typical buyer is not Italian.
They do not necessarily attend European reference trade shows.
They do not have a local agent connecting them to Italian manufacturers.
They do not have an established network with the relevant industrial districts.
They search online, in English and sometimes in other languages, looking for technical solutions to their production problem.
And here is the paradox:
Italian manufacturers have technically excellent products, specific know-how and customisation capability that few in the world can match.
But their online information is designed for those who already know them — not for those searching for them.
The Three Procurement Channels — And Where Each Works
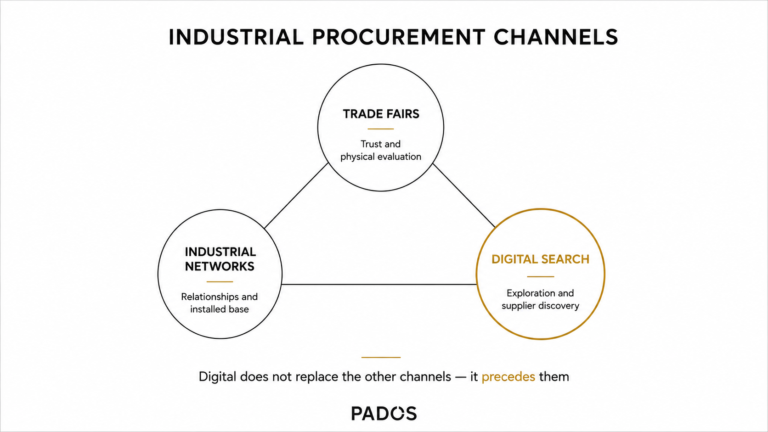
The analysis mapped how supplier selection actually works in this type of market.
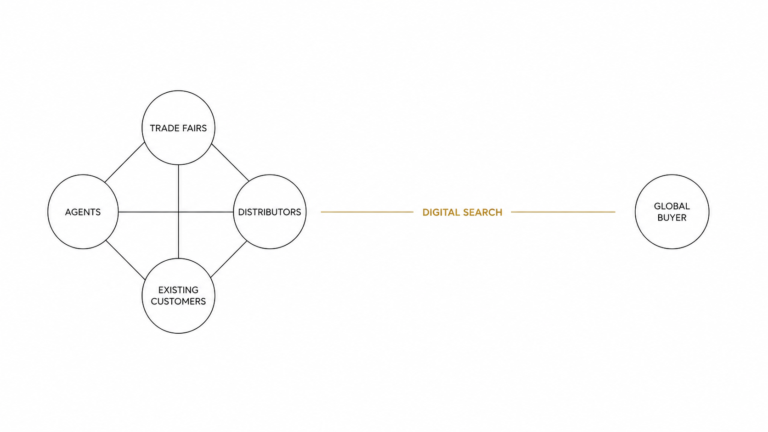
It is not a linear process, but a hybrid system with three channels serving different functions.
Trade fairs
Trade fairs are the place for trust and relationship.
Seeing the machine in operation, talking to engineers, physically comparing solutions — these are elements no website can replace.
Trade fairs work well for buyers who are:
- already in the market
- working with defined budgets
- looking for confirmation of already-oriented choices
Industrial networks
Agents, distributors, existing installed base, service.
This is the loyalty channel:
those who have already bought from a supplier tend to buy again, or receive internal referrals.
It works in markets where the company already has a presence and a network.
Digital search
Digital search is the initial exploration channel.
It does not replace the other two — it precedes them.
A buyer with no pre-existing relationships, evaluating options for the first time.
An integrator looking for qualified suppliers for a specific project.
A manufacturer expanding into a new process.
All of these profiles start online.
The relevant finding is that the digital channel reaches exactly the buyer that fairs and networks do not reach:
- new geographic markets
- new customers in existing markets
- new processes requiring machines the company has not previously supplied
Why Sector Websites Do Not Capture This Traffic
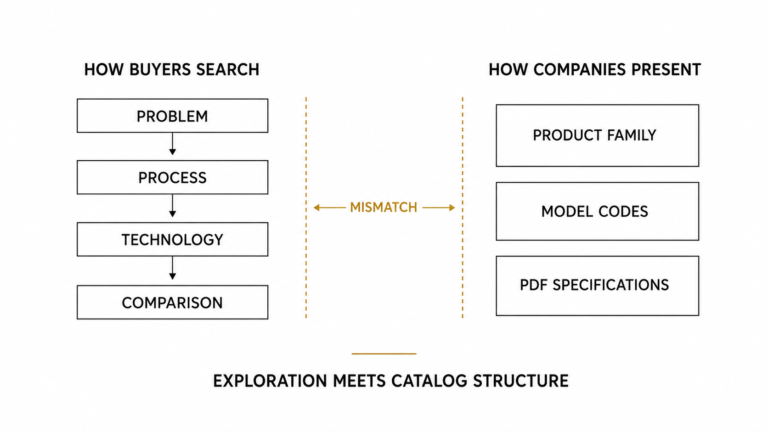
The analysis of an international sample of manufacturer websites produced a uniform picture.
The structure is that of a catalogue, not a selection tool
Products are presented by:
- family
- code
- production phase
This works for buyers who know the terminology and already know what to look for.
It does not work for those exploring.
These buyers are not yet sure exactly what they need. They search by problem to solve, not by machine name.
Technical specifications are present, but not comparable
Every manufacturer uses:
- different formats
- different parameters
- different units of measurement
A buyer wanting to compare three suppliers cannot do it without requesting additional documentation from each.
This increases:
- evaluation time
- operational effort
- the advantage of whoever makes comparison easier
International presence is declared, but not structured
Almost all manufacturers declare they export.
But they often do not publish:
- local offices
- distributors by market
- regional contacts
- service and spare parts information
A buyer in Vietnam, Brazil or Poland does not know:
- who to contact locally
- whether local service exists
- what response times look like
This information gap is a filter that eliminates the company from consideration before contact even occurs.
The Data Point That Changes the Perspective
In many manufacturing sectors, more than 45% of factories have already adopted automated systems to improve efficiency and quality.
And this percentage is rising.
This means two things simultaneously.
1. New buyers are entering the market
Facilities are evaluating their first automation.
These buyers:
- have no market experience
- have no pre-existing supplier relationships
- will necessarily start their search online
2. Existing buyers are re-evaluating the market
Facilities have already automated one line and are evaluating extensions to others.
These buyers:
- may already have a supplier
- are comparing alternatives
- are re-entering the exploration phase
Both profiles are potential buyers who search online before any other channel.
And in both cases, the manufacturer’s website is the first point of contact — or it does not exist as a point of contact.
Information Asymmetry as Competitive Advantage
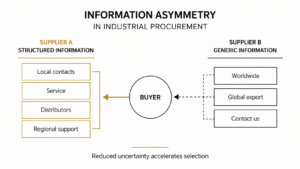
The clearest result of the analysis is this:
in a market where almost no one publishes structured information for the international buyer, the few who do stand out by default.
This is not about having better SEO or a more attractive website.
It is about answering the questions a foreign buyer asks when evaluating a supplier they do not know:
- Does this manufacturer operate in my market, or do I need to import directly?
- Is there local technical service, or do I manage everything from the manufacturer’s country?
- Can I understand whether the product suits my needs without requesting a consultation?
- Is the technical documentation available in a language I can read?
Companies that answer these questions on their website build a direct advantage in the selection phase.
This can include:
- pages organised by geographic market
- multilingual documentation
- published service networks
- comparable technical specifications
Not because of marketing budget.
But because they reduce friction in the evaluation process.
Knowing Your Sector’s Buyer Journey First Gives You an Unfair Advantage
There is a final observation that emerges from the analysis and is worth making explicit.
In a market where almost no one has mapped how buyers search, compare and decide, the first company that does gains a disproportionate advantage relative to the effort involved.
This is not:
- a technological advantage requiring enormous investment
- a product advantage requiring years of R&D
- a matter of having more resources
It is knowing something competitors do not know:
the real path a buyer takes before contacting a supplier in that specific sector.
This type of knowledge is difficult to replicate for two reasons.
First, it takes time to accumulate:
- real data
- real sessions
- real behaviour
Second, once translated into information structure, it produces cumulative effects.
The more a site answers buyers’ real questions:
- the more it gets found
- the more authority it accumulates
- the harder it becomes to overtake for those who start later
In the sector analysed, where the vast majority of manufacturers have not yet done this work, whoever starts today enters the market with an advantage that consolidates over time — not because they have more resources, but because they understood first how their buyer searches and decides.
See How Your Specific Situation Looks
The free PADOS assessment analyses:
- how buyers find your products
- where the evaluation process breaks
- which information is missing in the decisive phases of procurement
Thirty minutes. No commitment.
Analysis conducted on an international sample of specialised industrial machinery manufacturers — Italy, Europe, Latin America and Asia. Sources: company websites, company registries, export data and trade fair profiles. Companies are not named individually.